Banking · Explainer · 4 min read
Virtual accounts: where they help multi-entity cash visibility
Virtual accounts are sub-ledger accounts that sit under a physical bank account. They can reduce the number of physical accounts and simplify collections and reconciliation, but they do not remove the need for good structure, governance and local compliance review.
By Brian Weakliam ·
- Who this is for
- Treasurers, CFOs and payments operations teams in multi-entity groups.
- Why it matters
- Groups with many banks, accounts and transactions spend time and cost maintaining physical account structures that may be simplified.
Executive summary
- 1Virtual accounts sit beneath a physical account and segregate flows.
- 2They can help collections, reconciliation and account rationalisation.
- 3They need review against local and sector regulation.
What is the difference between virtual and physical accounts?
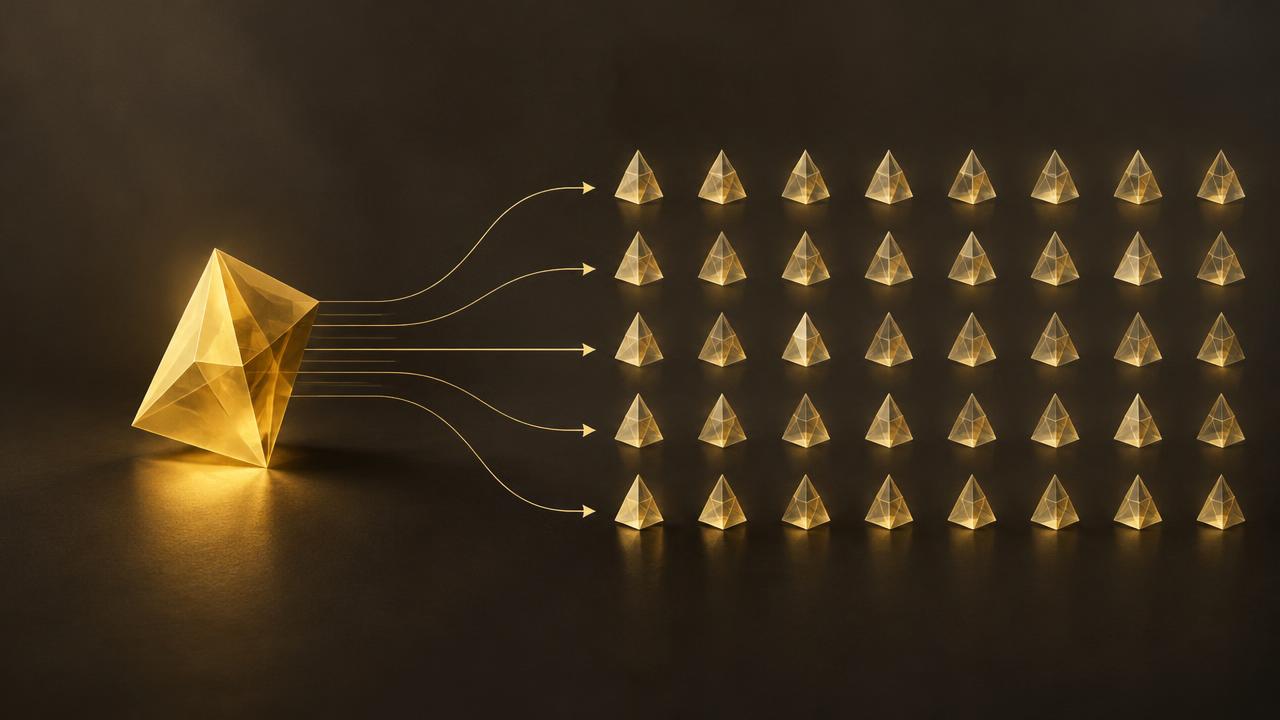
A physical account holds funds at a bank. Virtual accounts are references beneath it that allow incoming and outgoing flows to be identified and reported separately without opening more physical accounts.
Where can virtual accounts help?
- Reducing the number of physical bank accounts.
- Simplifying the cash management structure.
- Allocating incoming payments to customers or entities more easily.
- Supporting segregation of funds, for example in insurance premium collection and claims.
Where do they not help?
- They do not fix an unclear entity or banking structure on their own.
- They depend on what each bank offers and how it reports.
- They need review for compliance with local and industry regulation.
Sources and methodology
- Bankhawk perspective (2019, refreshed). Technology points to be updated.
Simplify your account structure
Tell us how many banks, entities and accounts you run. We will outline what a review would examine.
Discuss your banking arrangements